
You have ten days to close on an investment property. The bank won't finance it in its current condition, and the seller wants certainty, not another financing contingency. You need a lender who can assess the property, explain the cash required, and commit to a workable closing schedule.
A bridge loan is short-term financing secured by real estate. It helps you buy, refinance, or improve a property before selling it or arranging long-term debt. The best bridge loans fit the deal's timeline and repayment plan. The lowest advertised rate won't help if the lender can't fund the property or release renovation money when your contractor needs it.
These options serve non-owner-occupied investment properties only. Compare rates, loan-to-value limits, closing speed, renovation funding, and loan sizes, but start with your situation: rent-ready purchase, buy-and-rehab, cash-out refinance, or multifamily growth.
Keep business-property financing separate from personal borrowing decisions. If tax obligations are also affecting your liquidity, this discussion of personal loans to pay IRS debt explains a different borrowing decision. Don't assume a property bridge loan solves both problems.
1. LendingXpress

Best fit: Investors who need fast financing for an acquisition, refinance, or renovation on a residential or commercial property.
A tight closing, a property that needs work, or a refinance that can't wait for conventional underwriting calls for a lender that can assess the deal quickly. LendingXpress is a California-based private and hard money lender offering bridge, fix-and-flip, construction, and rental property loans.
Loan sizes typically range from $100,000 to $18 million and beyond. Most loan approvals are handled in 24 hours, and borrowers can receive funds in days, not weeks. Submit your request through the secure online portal, then provide the property details and repayment plan so the loan officer can assess the transaction.
Where the Flexibility Matters
For a buy-and-rehab deal, LendingXpress can finance up to 100% of rehab costs. Renovation funds are released through staged draws as work progresses, so get the draw schedule and required documentation in writing before closing.
Full rehab-cost coverage does not mean every project cost is covered. Ask for a breakdown of the acquisition advance, closing costs, interest carry, and cash needed before each draw.
- Advantages: Financing for residential and commercial properties, customized terms, and loan officers who answer questions about eligibility, terms, and the application process. Borrower feedback describes clear guidance, professional service, and fast closings.
- Trade-offs: Rates, fees, eligibility requirements, and detailed terms are set per transaction. Get a written quote for your property, including the total cash required and the repayment plan.
- Track record: LendingXpress has originated over $558 million in loans and holds California DRE license #02072559 and NMLS #1879867.
LendingXpress also offers trust deed investments and a debt investment fund with a 9% target annual return, secured by first-position liens on real estate. These are investment offerings, separate from borrower financing.
Choose LendingXpress when speed and a deal-specific structure matter more than comparing advertised rates. Use the pre-qualification tool to match your scenario with lenders, then review the written terms before committing.
2. Kiavi
Best fit: Residential acquisition-plus-renovation deals where you want a digital application and clearly advertised financing parameters.
Choose Kiavi for a residential investment property that needs work before sale or long-term financing. Its digital application, in-house valuation process, and broker channel make it a practical option for investors and intermediaries who want to screen a deal without starting with a lengthy bank process.
Kiavi's bridge-loan program advertises $75,000 to $5 million, 12-, 18-, or 24-month terms, rates as low as 8.25%, closings as fast as seven business days, and financing up to 100% loan-to-cost, 80% of after-repair value, and 100% of eligible rehabilitation costs, subject to program and underwriting.
Loan-to-cost, or LTC, compares the loan with eligible project costs. After-repair value, or ARV, is the estimated value after the planned improvements. These limits work together, so the highest advertised cost coverage doesn't mean every project qualifies for maximum funding.
Practical rule: Get the acquisition advance and renovation holdback shown separately. A large total commitment doesn't tell you how much money reaches closing.
What to Verify
- Advantages: Public terms help you assess project size, timeline, and financial position. Acquisition and eligible renovation financing can sit within the same transaction.
- Limitations: Kiavi focuses on investor residential property, not larger commercial assets. Maximum proceeds depend on the property and underwriting.
- Quote checks: Confirm cash to close, draw conditions, valuation assumptions, fees, and whether interest applies to undrawn renovation funds.
Kiavi is a strong shortlist choice for a straightforward residential rehab. Don't schedule contractors around an advertised closing time until the lender confirms that the file, title, and funding conditions are ready.
3. CoreVest
Best fit: Rental investors moving beyond isolated purchases into credit lines or multifamily financing.
CoreVest deserves attention when the financing question extends beyond the next house. It offers single-asset bridge loans alongside credit lines and multifamily bridge financing, giving growing operators several formats to evaluate.
CoreVest's bridge-loan programs advertise single-asset loans from $75,000 to $2 million or more, up to 100% of cost or 75% of value, interest-only payments, no prepayment penalty, and typical single-asset closings of two to four weeks, with nationwide lending subject to state exclusions.
Its single-asset product doesn't require a debt-service coverage ratio, or DSCR, test. DSCR measures whether property income covers debt payments. That can help when a rental property hasn't yet developed the operating history needed for permanent financing, but it doesn't eliminate other underwriting requirements.
Match the Product to the Portfolio
For a rental acquisition, start with the single-asset offering. For repeated purchases or multifamily growth, evaluate the relevant credit-line or multifamily program separately. Don't assume the single-asset limits and conditions apply across the whole product range.
- Advantages: Multiple financing formats and no-DSCR single-asset underwriting support investors with different operating plans.
- Limitations: The stated single-asset closing window isn't the right starting point for an emergency closing.
- Cost check: Rates and fees are quote-based. Compare the complete proposal rather than assuming a larger platform means cheaper financing.
Use this explanation of bridge-loan interest rates to distinguish pricing from the factors that influence it. CoreVest fits investors planning a financing relationship around portfolio growth, provided the specific product matches the collateral and deadline.
4. Lima One Capital
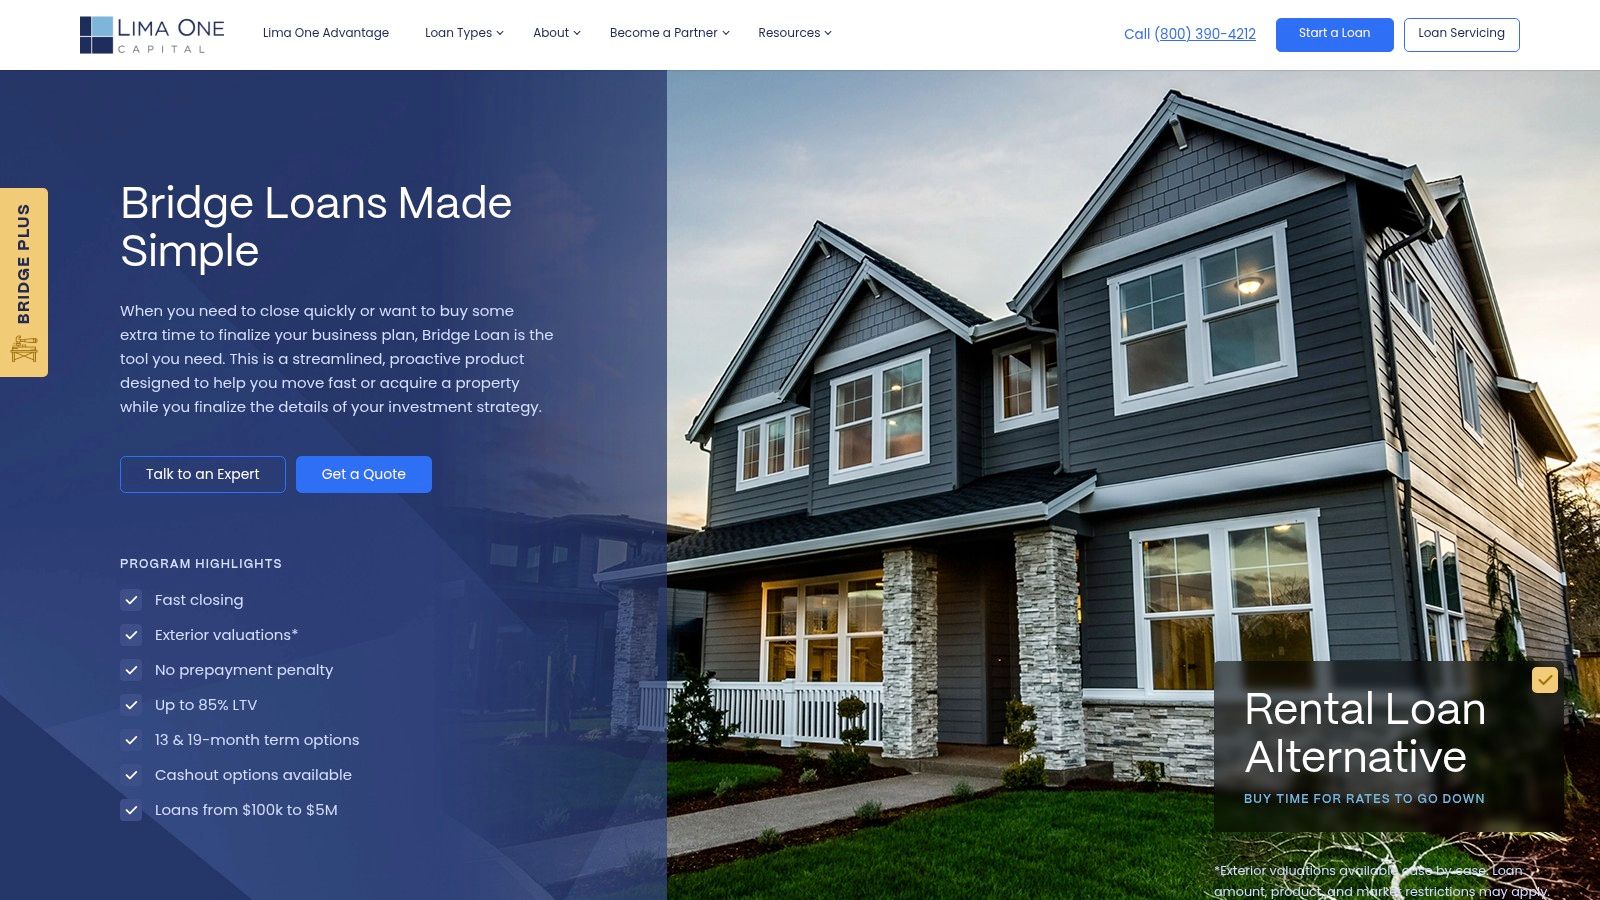
Best fit: A rent-ready purchase or cash-out refinance with no renovation budget.
Say you're buying a rental that's ready for occupancy, but permanent financing won't be available before closing. Lima One Capital's Bridge Plus is designed for that kind of gap. It can support an acquisition, refinance, or equity-access strategy without treating the property as a renovation project.
Lima One Capital's Bridge Plus program advertises $100,000 to $5 million, 13- or 19-month terms, interest-only payments, no prepayment penalty, and eligibility for non-owner-occupied single-family and 2–4-unit properties, with published qualification guidance calling for a 700 credit score.
The important distinction is condition: Bridge Plus doesn't include a rehabilitation budget. Lots and properties needing renovation belong outside this product's intended use, even if your plan is to finish the work quickly.
Choose the loan for the property you're buying today, not the property you expect to own after construction.
Why Rent-Ready Investors Should Consider It
- Advantages: A clearly defined rent-ready use case and no prepayment penalty suit investors who may sell or refinance early.
- Flexibility: Cash-out refinancing is available, and exterior valuations may be available in some cases.
- Limitations: The credit requirement narrows eligibility, and this product isn't a substitute for renovation or larger commercial financing.
Before choosing it, confirm that the lender accepts the property's present condition and your intended exit. Get the interest rate, origination charges, valuation requirements, and any minimum-interest provision in writing.
Choose Bridge Plus for a clean property and a defined short-term hold. If contractors need financing to make the property usable, select a renovation product instead.
5. RCN Capital

Best fit: Investors and brokers screening residential, apartment, or mixed-use collateral against published eligibility criteria.
RCN Capital is useful when you want to establish product fit before committing time to an application. It separates short-term bridge financing from renovation, rental, and construction programs, so property condition should drive your initial selection.
RCN Capital lists bridge loans of $75,000 to $3 million, 12- or 18-month terms, rates from 9.49%, a 650 minimum FICO, and purchase financing up to 80% of as-is value, with eligible collateral potentially including 1–4-unit properties and 5-plus-unit apartments, as well as condos, townhomes, and mixed-use properties.
As-is value means the property's value before your planned improvements. Refinance and cash-out limits are lower than the purchase maximum, so don't use acquisition financing to estimate equity-release proceeds.
Where RCN Fits
- Advantages: Published credit and debt criteria make early screening easier. Some apartment and mixed-use properties can qualify, expanding the options beyond standard residential rentals.
- Program distinction: Separate bridge and renovation offerings help match financing to the property's actual condition.
- Limitations: Pricing and borrowing capacity vary by transaction, and program details differ across company materials. Confirm the current product and loan limit in the written quote.
RCN lists no prepayment penalty for its short-term programs. Still, review minimum interest, origination charges, and payoff costs separately, because the absence of a prepayment penalty doesn't describe the entire cost.
Use this guide to bridge-loan fees to organize the comparison. Choose RCN when its published collateral and credit criteria align with the deal, then confirm the exact bridge or renovation program before relying on its headline terms.
6. Park Place Finance

Best fit: Rent-ready investment-property purchases or refinances where conventional income documentation is the obstacle.
Park Place Finance says its bridge product doesn't require tax returns, income verification, or a debt-to-income ratio. That makes it worth considering when your property and equity support the transaction but your personal income paperwork doesn't fit a traditional bank's process.
Park Place Finance's bridge program lists $100,000 to $5 million, 12–24-month terms, rates from 8.99%, 1–3 points, interest-only payments, and no prepayment penalty, with maximum advertised financing of 80% LTC for purchases, 80% LTV for rate-and-term refinances, and 70% LTV for cash-out refinances, plus a stated 660 minimum FICO with possible exceptions.
LTV, or loan-to-value, compares debt with the lender's accepted property value. Points are upfront loan charges. Compare both with the interest rate, especially if you expect a short hold.
Cash-out check: Start with estimated proceeds after the existing loan payoff and closing costs. The gross loan amount isn't the cash you can deploy.
Strongest Use Case and Main Limits
This is primarily a rent-ready residential investment option, not major commercial financing or a renovation facility. Properties needing work may fit the company's separate fix-and-flip product instead.
- Advantages: Published terms and pricing help with initial screening. Related DSCR and construction products offer alternatives for different strategies.
- Limitations: Reduced income documentation doesn't mean automatic approval. Property quality, credit, equity, and the exit still matter.
- Timing: Published closing statements vary, so get a deal-specific schedule rather than planning around the fastest promotional claim.
Choose Park Place for a rent-ready asset when documentation flexibility matters. Confirm the required cash contribution and net refinance proceeds before accepting the quote.
7. Easy Street Capital

Best fit: Residential bridge or fix-and-flip transactions with a complete file and a tight deadline.
Easy Street Capital's EasyFix combines bridge and fix-and-flip financing. Its advertised no-appraisal process is particularly relevant when valuation scheduling could otherwise interfere with closing, but no appraisal doesn't mean no property review.
Easy Street Capital advertises EasyFix rates from 8.90%, with broader materials listing 8.90%–10.90%, loan amounts of $100,000 to $2 million, 6–12-month terms, up to 85% LTC and 70% LTV, and closings as fast as 48 hours in some cases; its materials also list 2–3 points and a document fee.
Treat the fastest closing as a best-case outcome, not a commitment. Title issues, incomplete entity documents, insurance, missing signatures, or unresolved underwriting conditions can prevent an otherwise quick transaction from funding.
Speed Needs a Complete File
Easy Street is a direct lender with discretion over loan decisions. Its published materials provide a useful starting point for comparing loan size, borrowing capacity, and fees, and EasyFix lists no prepayment penalty.
- Advantages: A potentially fast process and no advertised appraisal requirement suit straightforward residential investment transactions.
- Limitations: State exclusions and transaction requirements restrict availability. The product isn't aimed at larger commercial assets.
- Quote checks: Confirm the actual term, current fee schedule, valuation process, renovation draw conditions, and what must happen before funds can be released.
Choose EasyFix when the property fits and your closing team is ready to act. Have the purchase contract, renovation scope, entity documents, insurance contact, and title contact prepared before requesting an accelerated close.
Don't let a fast acquisition create an unrealistic payoff deadline. The loan term must also leave room to complete the work and execute the sale or refinance.
How the seven bridge lenders compare on loan size, advertised rates, terms, and rehab financing
| Item | Loan Size | Advertised Rate | Term Length | Rehab Financing |
|---|---|---|---|---|
| LendingXpress | $100,000 to $18 million and beyond | Not published | Not published | Up to 100% of eligible rehab costs, funded through staged draws |
| Kiavi | $75,000 to $5 million | From 8.25% | 12, 18, or 24 months | Up to 100% of eligible rehab costs |
| CoreVest | $75,000 to $2 million or more | Not published | Not specified | Not specified |
| Lima One Capital | $100,000 to $5 million | Not published | 13 or 19 months | Not included in the bridge product |
| RCN Capital | $75,000 to $3 million | From 9.49% | 12 or 18 months | Separate renovation program available |
| Park Place Finance | $100,000 to $5 million | From 8.99% | 12–24 months | Bridge product targets rent-ready properties; fix-and-flip product available |
| Easy Street Capital | $100,000 to $2 million | From 8.90% | 6–12 months | Fix-and-flip financing available |
Pick the Bridge Lender That Fits Your Next Closing
The best bridge loans solve a specific financing gap without creating an unmanageable maturity. Choose a rent-ready bridge for a finished rental, a renovation facility for a buy-and-rehab, and a multifamily or credit-line product when the financing need extends across a growing portfolio.
For cash-out transactions, compare net usable proceeds, not just the approved loan balance. For deadline-driven acquisitions, get the lender's remaining conditions and closing responsibilities in writing. Advertised speed matters only when the property, borrower, title company, and funding team are ready.
Run the Buyer's Checklist on Every Quote
- Property and borrower fit: Confirm eligible property type, occupancy, state, borrowing entity, credit requirements, and experience requirements.
- Funding and cash to close: Identify the accepted value, acquisition advance, renovation holdback, equity contribution, and required reserves.
- Complete cost: Add interest, points, document charges, valuation costs, draw fees, minimum interest, and expected extension costs.
- Renovation access: Establish inspection requirements, reimbursement timing, contractor documentation, and who funds work before each draw.
- Maturity protection: Read extension conditions, extension fees, default pricing, and any required principal reduction.
- Exit evidence: Support the sale or refinance with realistic value, rental income, completion timing, and permanent-financing requirements.
Test a sale, permanent refinance, and an extension or recapitalization rather than relying on a single exit. A Principal Real Estate analysis found that 73% of CMBS loans scheduled to mature in 2025 paid off on time, illustrating why a planned refinance still needs supporting evidence.
Resolve title problems early, too. Although it addresses homeowners rather than investor-loan eligibility, this guidance for homeowners facing lien-related closing delays explains why liens deserve attention before the scheduled closing.
Start with our no-commitment Loan Pre-Qualification tool, which matches your scenario to lenders in seconds. Then email loans@lendingxpress.com with the property address, transaction type, requested financing, closing deadline, and specific questions before you apply. Our loan officers can also answer questions by text about eligibility, terms, and the application process.
LendingXpress offers bridge, fix-and-flip, and rental-property financing for non-owner-occupied residential and commercial investments. Visit LendingXpress to start a no-commitment pre-qualification and discuss a structure that fits your acquisition, refinance, or renovation plan.