
The most repeated advice about hard money and soft money is to line up the rates and take the lower one. That's the wrong first move. On the deals these loans finance, the rate rarely decides whether the borrower makes money.
A bridge loan costs what it costs. What sinks a project is a sale that closes in April instead of January, a refinance that stalls because the appraisal came in under the after-repair value, or a construction draw that waits two weeks for an inspector. Those are timeline problems, and no rate discount pays for them.
The decision that matters is the exit, not the coupon. What follows compares the two loan types side by side, prices a real hold down to the dollar, stress-tests the schedule at three, six and nine months, and gives you a rule for which structure fits the exit you have.
Two Meanings of Hard Money and Soft Money
In lending, “soft money” is not a legal loan category. The same terms also appear in campaign finance, where they mean something different.
Federal election law uses hard money for contributions raised from permissible sources and within permissible limits. Soft money refers to funds raised outside those source and amount limits, as described in the FEC filing in a campaign finance case. The OpenSecrets backgrounder on soft money explains that the Bipartisan Campaign Reform Act of 2002 barred national parties from raising soft money for federal election activity.
For property financing, hard money means short-term, asset-secured private lending, generally underwritten around the property and the borrower's exit plan. Soft money is industry shorthand for longer-term conventional investment financing. No statute defines the term for lending, and lenders use it loosely. It may describe a hybrid product or a conventional rental loan.
Check your intent first: If you're financing a rental, a flip or a refinance on a non-owner-occupied property, keep reading. Campaign contribution rules are a separate subject.
The shared terms can lead to unrelated search results. Here, both refer to property financing, and the practical distinction is how the loan is structured around the property and the planned exit.
Hard Money and Soft Money Side by Side
The exit date matters more than the label. A short-term loan can fit a property that needs work and a defined sale or refinance; long-term investment debt suits a stabilized rental that can carry payments over time.
| Factor | Hard money | Soft money (conventional investment loan) |
|---|---|---|
| Typical interest rate | About 9% to 14% on commercial deals | About 6% to 8% |
| Upfront fees | 1% to 5% origination points | Usually lower at origination, set by the lender |
| Loan term | 6 to 36 months | 15 to 30 year amortization, refinanced or sold later |
| Payment structure | Usually interest-only with a balloon payment at maturity | Principal and interest, fully amortizing |
| Qualifying basis | Property value and exit plan | Credit, verified income and debt-service coverage |
| Loan-to-value | About 60% to 75% | Limited by debt-service coverage rather than collateral alone |
| Closing speed | Days to a few weeks | Several weeks to two months |
| Best fit | Transitional assets that do not qualify conventionally | Stabilized rentals with reliable cash flow |
What each column is really pricing
Soft money is market shorthand for longer-term investment debt. It generally weighs borrower credit, verified income, debt-service capacity and stabilized property cash flow more heavily than collateral value, according to Stormfield Capital's comparison of hard and soft money. Conventional investment mortgages run near 6% to 8%; hard money commonly prices around 9% to 14% with 1 to 5 points at origination.
The payment structure changes the monthly comparison. On a $700,000 balance, a 7% fully amortizing 30-year loan carries principal and interest of roughly $4,657 a month. The same balance at 10% interest-only costs about $1,176 more each month, and the principal remains due at maturity.
Two borrowers, two columns
A leased fourplex, clean returns and a ten-year hold point toward conventional investment financing. The lower rate and long amortization reduce the monthly obligation. For rental financing routes, review LendingXpress rental property financing options.
A vacant building that needs months of electrical, drywall and roof work points toward hard money. The property may not qualify for conventional financing until the work is complete and income is established. The trade-off is a short repayment window: if construction or the sale runs late, the balloon still comes due.
The column test: Match the loan to the expected exit. Use long-term financing for a stabilized rental you plan to hold; use hard money when the property needs a short transition and you have a credible sale or refinance plan. An Edinhart Realty investor financing guide offers another perspective on how property managers and lenders assess an investment deal.
What Each Loan Costs Over a Real Hold
Start with one purchase and follow the money through a six-month hold.

Take a $1,000,000 property financed at 70% loan-to-value. The loan amount is $700,000, which means $300,000 of equity before a single transaction cost or rehab dollar, as Avana Capital's hard money and private money comparison lays out. At 10% interest-only, the monthly interest runs about $5,833.
Fees stack on top of the carry. A 2-point origination charge on $700,000 adds $14,000 at closing. Hold the loan six months and interest plus points come to roughly $49,000 before a dollar of principal comes back. That figure still leaves out inspections, legal fees, draw-related expenses, property taxes, insurance and any extension charge.
The premium buys something specific. It buys a closing date you control.
When the premium is worth paying
Hard money is economically rational when a delayed closing, an auction deadline, a construction schedule or a value-creation plan is worth more than the financing cost. A property that can't close in 30 days doesn't get bought at all. A rental that sits vacant through a five-month bank approval loses rent that no rate discount returns.
If you want the cost side broken down line by line before you call anyone, this explainer on what hard money lenders charge covers points, draws and extension pricing in plain terms.
A fully amortizing loan on the same $700,000 spreads repayment across 30 years and drops the monthly obligation, but it asks for income documentation, filed returns and a stabilized rent roll that a transitional property usually can't produce yet. That's the trade: you pay for speed and collateral underwriting, and you get a loan that doesn't care what your W-2 says.
Rule of thumb: multiply the monthly carry by the months you expect to hold, add points, then add exit costs. Compare that total against expected profit. If the profit disappears once carry and points come out, the deal isn't ready for either loan.
How Timing and Exit Risk Change the Math
The loan's maturity date can matter more than its monthly payment. Many hard money loans require interest-only payments and leave a balloon balance due at the end of the term. A borrower can make every monthly payment and still face a problem if the sale or refinance is not ready when repayment is due.
Extra interest cost when a hard money loan runs late
| Delay past plan | Extra interest on $700,000 at 10% | Typical cause |
|---|---|---|
| On schedule | $0 | Exit closes as planned |
| 3 months late | About $17,500 | Permit or contractor delay |
| 6 months late | About $35,000 | Appraisal below target or refinance slowdown |
| 9 months late | About $52,500 | Market slowdown and added extension fees |
The figures assume the $700,000 balance stays outstanding at a 10% annual rate. Three months of delay adds about $17,500 in interest; six adds about $35,000; nine adds about $52,500, before any extension fee.
An extension can add more than interest. One point on $700,000 is about $7,000, and an extension may also require a new appraisal and another lender fee.
Rate risk and execution risk are different animals
Rate risk changes the cost of financing. Execution risk changes whether you can exit on time. A slower, cheaper loan may miss a purchase deadline; a fast, expensive loan can become a problem if repayment depends on a sale price you cannot control.
Before closing, test a lower after-repair value, a 15% construction overrun, a weaker sale price, smaller refinance proceeds, and the cost of one extension. Then run the same deal with a six-month delay. If the project cannot cover the added carry and still repay the balloon, the planned exit is too fragile.
Before signing, answer one question: if the project runs six months late, what pays off the loan?
Tax and Occupancy Rules for Investment Loans
Two rules catch investors off guard on non-owner-occupied property, and both apply before and after closing.
Business-purpose credit and the 14-day line
Under the Consumer Financial Protection Bureau's rule, credit used to acquire, improve or maintain a rental property counts as business-purpose credit when the property isn't owner-occupied, whether it holds one unit or many, per the CFPB's Regulation Z commentary. The rule covers a warehouse leased to tenants and a single-family house rented to someone else.
The exception matters at application. That treatment doesn't apply if you expect to occupy the property for more than 14 days in the coming year, so a beach house you plan to use for a month is handled differently. State occupancy plans accurately.
Interest deductibility and records
IRS Publication 936 states that mortgage interest on a property other than your main or second home may be deductible when the loan proceeds are used for business, investment or another deductible purpose. If only part of the proceeds serves an investment purpose, only the allocable share of the interest is potentially deductible, and the usual limits still apply.
That creates a record-keeping job. Say $500,000 of a $700,000 loan buys the rental and $200,000 comes out as cash for something else. Only the share tied to the rental is a candidate for deduction, so keep the closing statement, the draw schedule and the bank trail showing where each dollar went.
Lending decisions and tax treatment are separate questions. Confirm your position with a tax professional before you build a deduction into your return.
Checklist Before You Sign a Loan
Get these ten answers in writing before you compare offers. A verbal answer from a broker is not the term you'll close on.
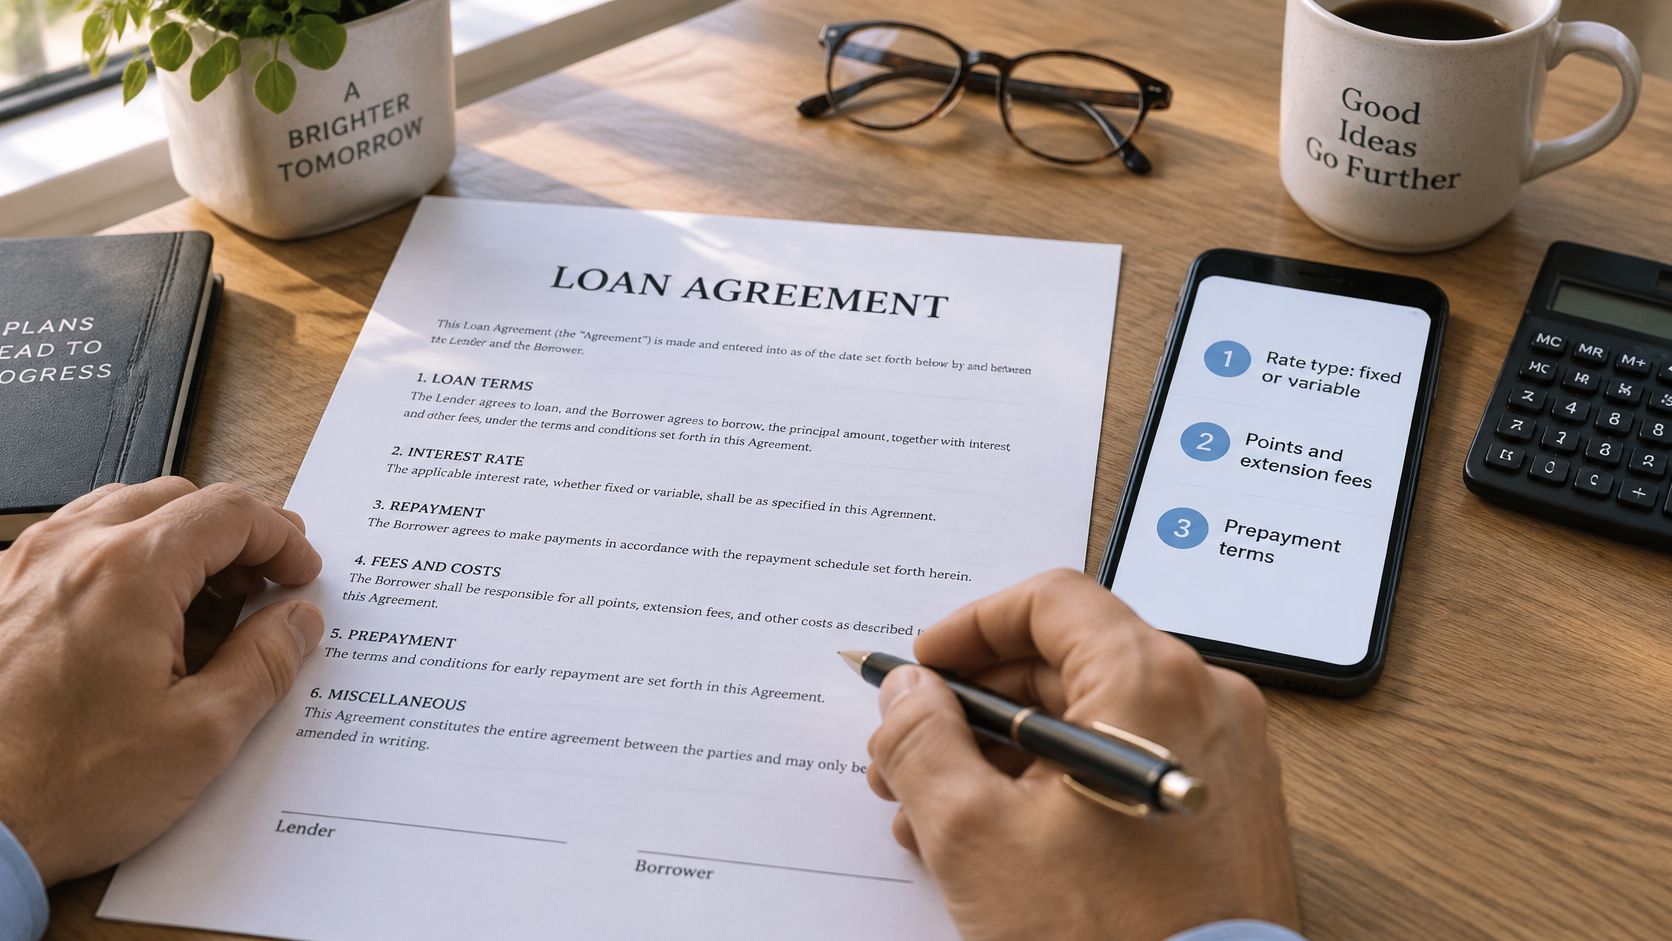
- Rate type and index. Fixed or variable, and if variable, which index it follows and how often it resets. A vague answer about "market conditions" is the red flag.
- Points and extension pricing. How many points come out at closing and what one extension costs. "We'll work with you" is not a number.
- Maturity date and balloon amount. The calendar date and the exact payoff due. A lender who can't state the balloon figure is telling you something.
- Prepayment penalty. Whether selling early or refinancing triggers a charge, and how it's calculated. A minimum interest period is the common form.
- Draw schedule. How rehab funds release, what each draw requires and how many business days an inspection takes. Slow draws stall more projects than rates do.
- Appraisal basis. As-is value or after-repair value, since the answer changes both the loan amount and your cash to close.
- Default and cure periods. How much notice you get before a late payment becomes a default, and how long you have to fix it. Silence here is a real risk.
- Fees at closing. Appraisal, inspection, legal, servicing, wire and anything labeled admin. Ask for dollar figures, not ranges.
- Reserves required. The cash you must hold after closing and whether retirement accounts count toward it. Lenders differ, so write it down.
- Occupancy. Confirm in writing that the loan is for a non-owner-occupied property. An ambiguous answer can void your rate.
Answers in writing turn a sales pitch into a term sheet you can compare line by line against another lender's.
Which Financing Fits Your Deal
Five situations, each with the trigger that should push you toward the other product.
- Auction flipper facing a 10-day close with a rehab budget. Hard money, because approval rests on the property and the plan rather than your income file, and the deadline is the whole deal. If the auction is 60 days out and the building is already rentable, price a conventional loan too and keep the hard money quote as a fallback.
- Vacant duplex that needs six months of work. A short bridge now, refinanced into conventional debt once it's leased and stabilized. Skipping that refinance is how investors renew a 12-month loan year after year at bridge pricing.
- Stable rental, strong credit, verifiable W-2 income, multi-year hold. Soft money. The lower rate and long amortization reduce the monthly payment, and there's no balloon to race.
- Self-employed buyer whose returns show modest income but whose assets are real. Private or hard money now, refinance once the income is documented across two years of filed returns.
- Cash-out after a renovation. Bridge against the improved value, then a long-term loan to reset the payment. Watch the seasoning requirement and the updated appraisal before you count on the second loan.
The rule I'd apply: if the exit is a sale or refinance inside twelve months and the deal doesn't hinge on a low rate, hard money fits. If the plan is a long hold with stable rent and documented income, soft money costs less over the life of the asset. If the exit is uncertain, bridge first and move to conventional only after the work is done, the income is stabilized, the valuation is updated and debt-service coverage is met.
Write down three things before you sign anything: the exit event, the date it happens, and the buffer you need if it slips. Then confirm you can carry six months of payments, points and one extension without running out of cash.
As a California-based private and hard money lender, we underwrite the exit alongside the property, and our hard money, fix and flip, construction and bridge loans are sized for timelines a bank can't move on. Bring the timeline before you commit to a term sheet. A loan officer who asks when your exit closes is more useful than one who quotes you a rate.
LendingXpress structures hard money, fix and flip, construction and bridge loans for investors buying non-owner-occupied residential and commercial property in California, with underwriting built around the property and your exit rather than a W-2. Bring us your purchase price, rehab budget, exit date and the reserves you're holding, and we'll tell you which structure clears and what happens to the math if the timeline slips six months. Visit LendingXpress to submit a property or talk through your exit with a loan officer.